Financial progress is often associated with major decisions such as buying a home, choosing investments, or planning for retirement. Yet many financial outcomes are shaped by smaller choices repeated over months and years. Daily spending, subscription management, emergency savings, and payment habits can gradually influence how much flexibility a household has when circumstances change.
This makes personal finances less about finding one perfect strategy and more about building systems that are easy to maintain. When financial habits are designed around realistic income, recurring expenses, and personal priorities, small improvements can accumulate without requiring dramatic lifestyle changes.
Building flexibility into the monthly budget
A budget should do more than assign every dollar to a category. It should also create room for unexpected expenses and changing priorities. A financial plan with no flexibility can become difficult to maintain when transportation costs rise, household repairs appear, or income temporarily changes.
Leaving room for irregular expenses
Many expenses are predictable even when they do not occur every month. Annual memberships, vehicle maintenance, insurance payments, school costs, and seasonal purchases can create sudden pressure when they are ignored during monthly planning.
Setting aside a small amount regularly for these expenses can make them easier to absorb. Instead of treating each large bill as an emergency, consumers can gradually build reserves for costs they already know are likely to occur.
Making cash reserves part of financial planning
Emergency savings can provide more than protection from unexpected bills. A cash reserve can also give households greater freedom when financial circumstances change. It may reduce the need to rely immediately on credit cards or high-cost borrowing when an unexpected expense appears.
Setting a realistic savings target
There is no universal savings amount that works for every household. Someone with stable income and predictable expenses may have different needs from a person whose earnings fluctuate or whose essential costs are difficult to reduce.
Rather than focusing exclusively on a large final target, consumers can establish smaller milestones. Reaching an initial reserve can create momentum, while continued contributions gradually strengthen financial resilience.
Reviewing recurring expenses with fresh eyes
Recurring payments can quietly influence a budget because they often require little attention after being established. Streaming services, memberships, software subscriptions, delivery programs, and other automatic charges can remain active long after their usefulness has declined.
Turning forgotten payments into savings
A periodic review of recurring expenses can reveal opportunities to redirect money toward more meaningful priorities. Canceling even a few unused services may free cash for savings, debt reduction, or planned purchases.
The goal is not to eliminate every convenience. Instead, consumers can evaluate whether each recurring expense still provides enough value to justify its place in the monthly budget.
Giving financial goals a specific purpose
Saving money can become easier when a balance has a clear purpose. A general savings account may provide useful flexibility, but separate goals can make progress more visible and encourage consistent contributions.
Connecting money with future priorities
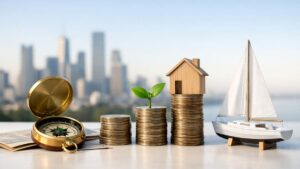
A household might save for travel, education, a vehicle, home improvements, or a future career change. Assigning a purpose to each goal can make financial decisions more tangible because every contribution becomes connected to something specific.
Priorities may also change over time. Reviewing goals periodically allows consumers to redirect money when circumstances evolve rather than continuing to save automatically for an objective that no longer matters.
Using automation to reduce financial friction
Good financial habits do not always require constant attention. Automation can help turn intentions into recurring actions by scheduling transfers, bill payments, and savings contributions around predictable income dates.
Automatic systems are especially useful because they reduce the number of decisions required each month. Once essential payments and planned savings are accounted for, the remaining money becomes easier to evaluate as discretionary spending.
However, automation should not replace financial awareness. Accounts still need to be reviewed regularly to ensure that income, expenses, subscriptions, and savings targets remain aligned. A system works best when it is automated but periodically adjusted.
Financial stability is rarely created by one extraordinary decision. More often, it develops through repeated choices that protect cash flow, reduce unnecessary expenses, and preserve room for unexpected circumstances. The advantage of this approach is that it does not require every financial decision to be perfect.
Small improvements can also become increasingly valuable when they are maintained over time. A modest recurring savings contribution, a canceled subscription, or a better system for handling irregular expenses may seem insignificant individually. Together, these choices can create additional flexibility and reduce the financial pressure associated with unexpected events.
The most practical financial strategy is therefore one that can survive ordinary life. Budgets should account for imperfect months, savings goals should reflect realistic circumstances, and financial systems should be simple enough to maintain consistently. When planning becomes part of everyday behavior, financial progress becomes less dependent on motivation and more dependent on structure.
Long-term financial health is not simply about earning more or spending less. It is about creating a relationship with money that supports flexibility, preparation, and meaningful goals. Small decisions may not produce dramatic results overnight, but their cumulative effect can significantly influence how confidently a household handles the future.